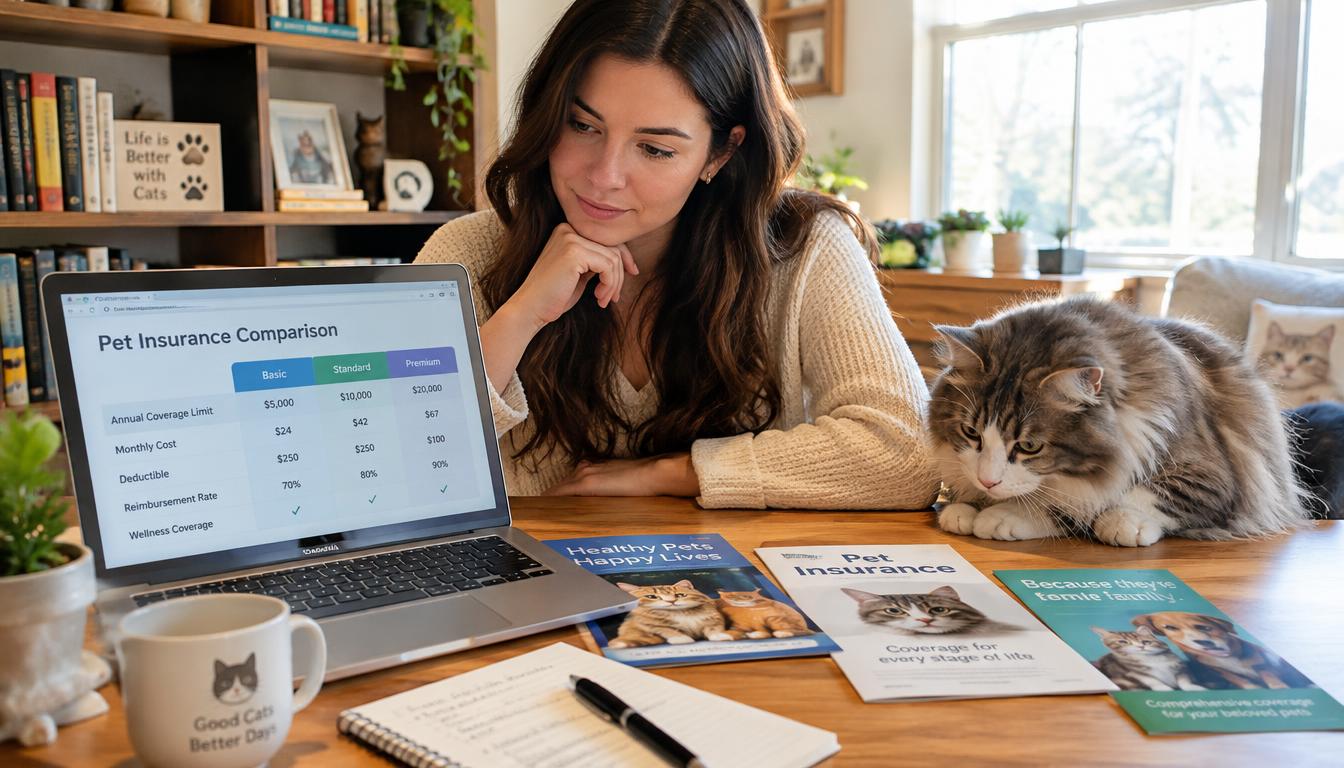
The best starting point for most cat owners is broad accident-and-illness coverage, then a comparison of exclusions, deductibles and annual limits. Cat accident-and-illness coverage averaged $32.21 per month in 2024, though individual quotes can differ. The reimbursement rate is the percentage of eligible veterinary expenses the insurer repays after the deductible applies.
We compare pet insurance companies by the care they cover, the bills they exclude and the share owners may pay themselves. ASPCA is the strongest all-around match in this comparison. Lemonade is a budget-focused alternative, while MetLife suits households insuring multiple pets.
A policy’s value also depends on its deductible, reimbursement rate and annual coverage limit, the most the policy pays in a year. We’ll help you compare those terms with the cost and your cat’s needs, rather than picking a plan by its headline price. Choose a premium you can keep paying, not just one that looks affordable for the first month.
Key Takeaways
- Compare accident-and-illness coverage, exclusions and policy limits.
- ASPCA is our broad-coverage pick in this comparison.
- Lemonade is a budget-focused option, and MetLife suits multi-pet homes.
- Match deductibles and reimbursement rates when comparing quotes.
- Choose a monthly premium that fits your long-term budget.
Best Pet Insurance for Cats by Coverage Need
ASPCA is our broad-coverage pick, while Lemonade and MetLife are stronger starting points for budget-minded and multi-pet households. Spot, Figo, Pets Best and Prudent Pet also stand out for specific coverage options. Ratings can differ because reviewers weigh price, coverage and service in different ways.
The strongest all-around match
ASPCA earns the broad-coverage spot here, but the best pet insurance for cats in the USA depends on your cat and budget. One comparison gave ASPCA 5 stars, Spot 4.8, MetLife 4.7 and Pumpkin 4.3. A separate 2026 comparison named Prudent Pet its 5-star overall pick.
Prudent Pet offers $10,000 or unlimited annual coverage, reimbursement choices of 70%, 80% or 90%, and deductibles from $100 to $1,000. Those choices help explain why insurance companies 2026 lists may rank the same provider differently. Nationwide also offers plans for eligible birds, rabbits, reptiles and small mammals, along with cats and dogs.
Ratings can help build a shortlist, but the scoring method changes which company comes out on top.
Other picks for budget, multiple pets and specialty needs
The table compares five pet insurance companies by fit, a concrete feature and a limitation to check. Pets Best suits owners who value mobility equipment; Figo may suit those seeking higher reimbursement choices.
| Company | Best fit | Distinguishing feature | Limitation to check |
|---|---|---|---|
| ASPCA | Broad coverage | Eligible exam fees and alternative therapies | Confirm each treatment meets policy terms |
| Lemonade | Budget-focused shoppers | Accident, illness and orthopedic coverage | State availability and waiting periods |
| MetLife | Multiple pets | Family plan for up to three pets | Check shared deductible and limit |
| Spot | Unlimited annual coverage | Unlimited annual limit option | Compare the price for that limit |
| Pets Best | Mobility needs | Covered prosthetics and wheelchairs | Check equipment eligibility and claim terms |
For the best pet insurance for cats in 2026, use ratings as a starting point, not a promise of fit. Treat a rating as a shortlist tool, then check the policy wording for your cat’s needs.
What Does Cat Insurance Cover, and What Is Excluded?
Accident-and-illness insurance can help with eligible treatment for an unexpected injury or disease, but it does not pay every veterinary bill. A typical policy may cover injuries, infections, chronic illnesses, diagnostics, hospitalization, surgery and prescribed medication. Coverage depends on the policy’s definitions, exclusions and benefit limits.
Eligible accidents, illnesses and treatments
Most plans reimburse 70%-90% of eligible expenses, up to the annual coverage limit. Owners commonly pay the vet first, then file a claim for reimbursement. Some plans offer direct payment, though the clinic must be able to use that process.
Some policies include behavioral care or alternative therapy, such as acupuncture. Others may offer end-of-life benefits. A policy may cover a treatment only when a vet links it to an eligible condition and the plan includes that service.
The nonprofit Best Friends coverage overview explains how accident and illness plans differ from routine wellness care. That distinction matters when a cat needs an exam but has no injury or disease.
Common exclusions to check
There is no best pet insurance for cats that covers everything. The phrase “everything covered” overlooks exclusions, benefit limits and the policy’s definition of an eligible condition. Common exclusions include:
- Pre-existing conditions
- Routine wellness care
- Breeding-related costs
- Some bilateral conditions affecting both sides of the body
- Preventable illnesses
Insurers may define the same diagnosis or symptom in different ways. A condition that began before enrollment may remain excluded even when new treatment starts later. Review the actual terms for diagnostics, follow-up visits and medication, not just the headline list of covered services.
Read the exclusions alongside the covered-treatment list before deciding that a benefit applies.
How Much Does Cat Insurance Cost?
Cat insurance commonly costs tens of dollars a month, but the reported average changes with the plan type and sample being measured. A 2026 NAPHIA-based estimate puts the average U.S. cat premium at $36 per month. These figures describe different samples and policies, not guaranteed quotes.
Average premiums are not directly comparable
The figures below use different years, samples and policy profiles, so they are not interchangeable quotes. MetLife reports a 2026 average and starting price, while other rows reflect plan types or a consumer survey.
| Benchmark | Monthly amount | What the amount represents |
|---|---|---|
| 2026 NAPHIA-based cat average | $36 | Average U.S. cat premium estimate |
| 2026 MetLife average and starting price | $28 average; $7 starting | Reported average and advertised starting price |
| 2024 accident-and-illness average | $32.21 | U.S. cat accident-and-illness coverage |
| 2024 accident-only average | $9.17 | U.S. cat accident-only coverage |
| Consumer Reports median for one cat | $34.50 | One cat and no other pet, from a survey |
A comparison using $5,000 in annual coverage found monthly averages of $29 for ASPCA and $27 for Spot, MetLife and Pumpkin. For $5,000 coverage, example prices for 4-month-old, 2-year-old and 8-year-old cats were $21, $26 and $36 per month.
What changes a cat’s quote?
For unlimited coverage, those same age examples were $32, $31 and $93 per month. Age, breed, sex, location and selected coverage affect premiums. Some companies charge at least $1 monthly to pay in installments.
A lower quote can be useful when its deductible, limit and exclusions still fit the household’s budget. The 2026 MetLife average and starting price also show why a starting price should not stand in for a cat-specific quote.
Compare quotes using the same cat profile, deductible, reimbursement rate and annual limit.
How Should You Set Your Deductible and Annual Limit?
A useful plan setting is one that leaves you able to pay the deductible and any bill above the annual limit. A higher annual coverage limit can protect against larger eligible expenses. Choose settings you could manage during a costly year, not only settings that lower the premium.
Choose the annual limit around your risk tolerance
Leading plans may offer annual coverage from $2,500 to unlimited. A higher limit gives the insurer room to reimburse more eligible care during the policy year, but it may raise the premium. A lower limit leaves you responsible for eligible costs above that cap.
Think about whether you could cover a large bill after the policy reaches its limit. A cat needing repeated treatment may use more of the annual limit than a cat with one brief visit. Your choice should reflect both your emergency savings and the treatment costs you could face.
Balance the deductible and reimbursement rate
A higher deductible usually lowers the premium, but you pay more before reimbursement applies. A higher reimbursement rate can increase the price while reducing your share of eligible bills after the deductible. Typical reimbursement rates range from 70%-90%.
For a fair test, request low-, middle- and high-deductible quotes with the same annual limit and reimbursement rate. For example, compare three deductible choices while holding a $10,000 limit and 80% reimbursement constant. The resulting prices show the deductible’s effect without changing other settings.
Claim calculations can be deductible-first or reimbursement-first. ASPCA, Spot and Pumpkin use a deductible-first calculation in one comparison, so the same stated rate may not yield the same payout across plans. Check these terms:
- Annual coverage limit
- Deductible
- Reimbursement rate
- Claim calculation method
Check the claim formula before comparing two policies with the same reimbursement percentage.
How Long Are Pet Insurance Waiting Periods?
Illness coverage commonly starts after 14 days, while some orthopedic conditions can remain excluded for months. In 2026, most major U.S. insurers have a 14-day illness waiting period. Trupanion’s illness wait is 30 days.
Accident and illness waiting periods
A waiting period is the time between buying a policy and the start of a benefit. Accident coverage may begin sooner than illness coverage, but the exact rule depends on the policy. State rules or policy terms can change the dates that apply.
Orthopedic and cruciate ligament delays
Orthopedic waiting periods range from 14 days to six months. The table shows how provider rules can affect when a cat’s care qualifies.
| Coverage type or provider | Waiting period | Practical implication |
|---|---|---|
| Typical illness coverage | 14 days | Illness benefits start after the wait |
| Trupanion illness coverage | 30 days | Longer illness delay than the common period |
| Orthopedic conditions | 14 days to 6 months | Check the condition-specific start date |
| Spot and ASPCA orthopedic coverage | 14 days | Shorter listed orthopedic wait |
| Embrace and Companion Protect orthopedic coverage | 6 months | Longer delay for orthopedic benefits |
Embrace has a 14-day illness wait and a 180-day orthopedic waiting period. A policy may set separate dates for accidents, illnesses and specific conditions, so one start date does not cover every benefit.
The Lemonade waiting periods include a 0-day accident wait, a 14-day illness wait and a 30-day orthopedic wait. Confirm the effective date for each coverage type in the policy, not just the purchase date.
Can Pet Insurance Cover Pre-Existing Conditions?
A prior diagnosis usually stays excluded, although some insurers may reconsider certain curable conditions after a symptom-free period. Figo may review a curable condition after 12 months without signs or symptoms following its last treatment. Enrollment alone does not make a prior condition eligible for reimbursement.
Curable conditions and symptom-free periods
Figo says a prior condition does not bar enrollment, but treatment for that condition may not be reimbursed. Its curable examples include vomiting, diarrhea, respiratory infection, kidney infection, urinary tract infection and ear infection.
Conditions that are usually excluded
Figo lists cancer, diabetes, orthopedic conditions, heart disease, kidney disease, urinary blockage, allergies, epilepsy and arthritis as incurable examples. Rules differ by company and by the cat’s records.
| Condition type | Examples | Possible requalification rule |
|---|---|---|
| Curable, Figo examples | Vomiting, diarrhea, ear infection | 12 months without signs after last treatment |
| Incurable, Figo examples | Diabetes, cancer, arthritis | Usually excluded as pre-existing |
| Curable, ASPCA and Spot | Some resolved conditions | 180 days without symptoms or treatment |
| Previously excluded, AKC | Some pre-existing conditions | 365 days of continuous coverage and renewal |
ASPCA and Spot may cover certain curable conditions after 180 days without symptoms or treatment. AKC may cover initially excluded pre-existing conditions after 365 days of continuous coverage and renewal.
Figo is among the policies to check for its 12-month symptom-free rule. Figo, ASPCA, Spot and AKC are worth comparing for their different curable-condition rules, not as cover for every pre-existing condition.
Ask the insurer to confirm in writing how the cat’s specific medical record affects eligibility.
Is ASPCA Pet Insurance a Good Choice for Cats?
ASPCA is our strongest all-around cat pick for owners who want a broad mix of medical and treatment benefits. Its plans can cover eligible accidents, illnesses, hereditary conditions, behavioral issues, exam fees, diagnostics and treatment. Its reimbursement rate can reach 90%, depending on the selected plan.
That 90% is a maximum, not a promise to repay 90% of every bill. The selected deductible, annual limit, reimbursement rate and policy terms shape each claim. Exam fees and diagnostics qualify only when the expense meets those terms.
Covered services can include dental disease, accident-related tooth extractions and alternative therapies such as acupuncture, chiropractic care and hydrotherapy. Policyholders can use licensed veterinarians in the United States or Canada. Those details can matter when a cat needs ongoing care from a specialist.
ASPCA also offers accident-only coverage and optional preventive-care coverage. Preventive options may include vaccines, dental cleanings, spaying or neutering and annual checkups. Routine benefits are separate from treatment for an eligible illness or injury.
Broad coverage does not mean every service qualifies. A dental procedure, behavioral visit or diagnostic test must meet the policy’s definition and other claim rules. Before enrolling, check whether the exact dental, behavioral and preventive expenses you expect are eligible.
Is Lemonade Pet Insurance Affordable for Cats?
Lemonade is a budget-focused option, but its price is only useful if the policy’s eligibility rules and waiting periods fit your cat. Its accident waiting period is 0 days, its illness wait is 14 days and its orthopedic wait is 30 days. A low premium cannot make an excluded benefit useful.
Lemonade policies can be bought for kittens from 2 months old. Cats at least 1 year old need medical records from the previous 12 and a half months. Pre-existing conditions with signs, a diagnosis or treatment before the policy or during a waiting period are not covered.
Preventive coverage begins on the policy effective date when that option is included. Breed-related age eligibility may also affect which policy a cat can get. Check these items before comparing the quote:
- State availability
- Breed-related age eligibility
- Accident, illness and orthopedic waiting periods
- Pre-existing-condition wording
- Required medical records
Some providers, including Lemonade, use a six-month cruciate-ligament wait. Preventive-care add-ons at Lemonade and Pumpkin often take effect immediately in 2026, while accident coverage starts immediately or by midnight after enrollment in some cases.
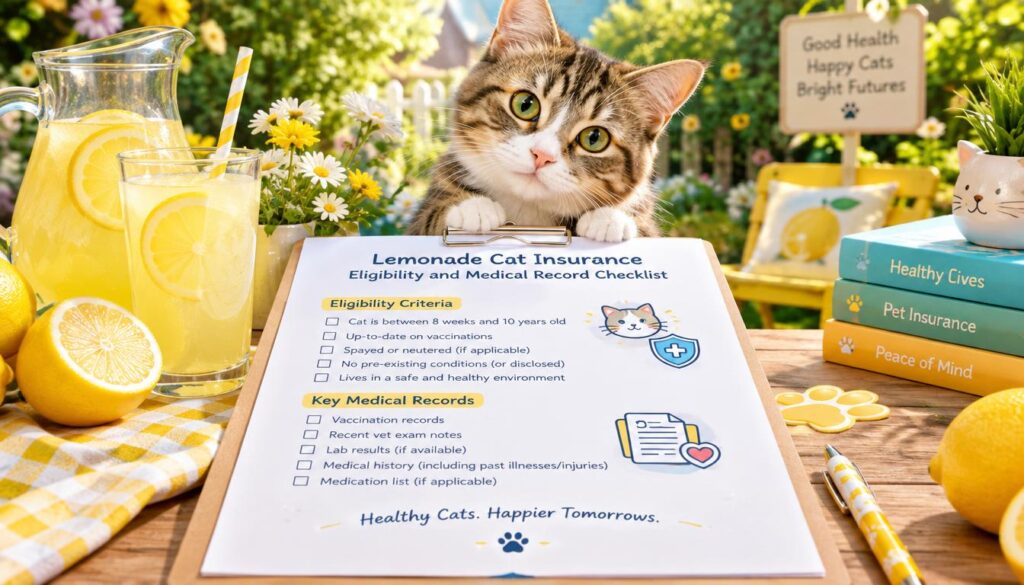
Check the state-specific quote and policy documents before relying on an advertised starting price.
How Does MetLife Work for Multi-Pet Homes?
MetLife is especially worth comparing when one household wants to manage coverage for several pets under a shared plan. Its family plan can cover up to three pets with a shared deductible. A shared deductible can simplify planning, but several claims may draw on shared resources.
MetLife offers annual-limit and deductible choices, with reimbursement rates up to 90%. A household can shape the policy around its pets, but the selected settings still affect the premium and claim payments.
A shared deductible may be easier to track than separate deductibles for each pet. Yet a shared limit and deductible can affect how much is available when multiple pets need care in one year. Ask how claims for each animal use the shared amounts.
MetLife has no upper-age restriction for enrolling a pet. That rule allows older animals to apply, but it does not mean each pet receives the same quote or coverage terms.
Before choosing the family plan, compare its annual limit with the likely needs of every covered animal. Confirm whether the shared limit is per pet or for the whole family plan before buying.
Figo vs. Pets Best: Which Suits Your Cat?
Figo stands out for higher reimbursement choices, while Pets Best has a useful edge for covered mobility equipment and requested vet payment. Figo offers reimbursement choices up to 100% and an unlimited annual payout option. Pets Best covers veterinarian-prescribed prosthetics and wheelchairs for covered conditions.
Figo for reimbursement flexibility
Figo may suit owners who want to limit their share of eligible bills after the deductible. Its 100% reimbursement option and unlimited annual payout option can appeal to households planning for costly treatment. The policy terms still decide which expenses qualify.
Figo has a 1-day accident wait and a 14-day illness wait. Compare the deductible as well as the reimbursement rate, since those settings affect what the owner pays on claims.
Pets Best for mobility equipment and vet payment
Pets Best may fit a cat whose covered condition could require mobility equipment. It offers direct payment to vets upon request. The clinic must be able to use that process, so do not assume the feature works everywhere.
Pets Best covers pets as young as 7 weeks and has no upper age limit. That enrollment range may help households considering coverage for a kitten or older cat, but the cat’s history and policy settings still matter.
Compare deductibles and ask your clinic whether it can use the insurer’s direct-payment process before treating that feature as a cash-flow solution.
When Do Spot, Pumpkin, or Healthy Paws Fit?
Spot is worth a look for unlimited coverage, Pumpkin for its coverage choices and preventive-care options, and Healthy Paws for standard alternative-treatment benefits. Each company’s standout feature comes with a policy tradeoff to check.
Spot for unlimited annual coverage
Spot offers an unlimited annual coverage option and 24/7 telehealth. It has no upper age limit, which can help older cats apply. Its accident and illness waits are 14 days, and its orthopedic wait is also 14 days.
Spot’s unlimited annual option may suit owners concerned about a large year of eligible claims. Compare the premium for the limit you want, rather than assuming the unlimited option costs close to a capped plan. Spot also has bilateral exclusions, so check how the policy treats conditions that affect both sides of the body.
Pumpkin for a preventive-care add-on
Pumpkin offers annual coverage limits of $10,000, $20,000 or unlimited, plus a 90% reimbursement option. Its preventive-care packages can help pay for planned services, but they are not the same as insurance for unexpected injury or illness.
Routine care includes services such as checkups and vaccines. An add-on may repay set amounts for listed services, so compare its schedule with the care your cat is likely to receive. A preventive option is most useful when its covered services match your expected visits.
Healthy Paws for alternative treatment
Healthy Paws includes alternative care in its standard accident-and-illness plan. Its accident and illness waits are 15 days, and its hip dysplasia wait is 12 months. Healthy Paws does not offer wellness plans.
That combination may suit an owner who values alternative treatment more than routine-care benefits. The longer hip dysplasia wait matters when a cat’s care may involve that condition, so read its terms before enrolling.
The Best Friends guide to routine care and insurance explains why preventive services differ from unexpected treatment. Match the distinctive benefit to a likely need, then check the exclusions that apply to the same condition.
Can You Insure an Older Cat?
An older cat can still qualify for coverage, but the available plans and premium may be less favorable than for a kitten. Enrollment eligibility, premiums and exclusions depend on the policy and the cat’s history. Age-based prices can rise sharply for some coverage choices.
One comparison found that ASPCA’s monthly rate for a $5,000 policy rose $15 between kitten and senior-cat profiles. Across cat insurers, the average difference in that analysis was also $15.
Unlimited coverage showed larger gaps in some examples. Spot’s average kitten-to-senior difference was $73, compared with a $61 national average. Pumpkin’s difference was $74 against the same average.
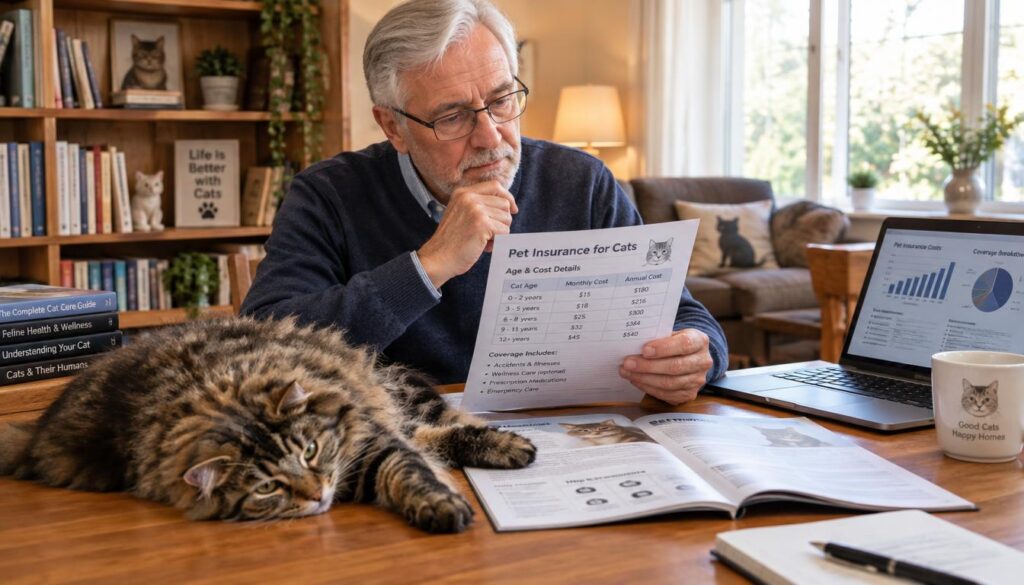
Those examples show why owners should get quotes for their own cat rather than assume a market average applies. A cat’s medical history may also affect which conditions a policy covers.
Before comparing plans, check:
- New-enrollment age limit
- Pre-existing-condition review
- Renewal pricing
- Waiting periods
Get a quote using the cat’s current age and disclose known conditions accurately.
Should You Add Wellness or Choose Accident-Only Coverage?
Wellness coverage is for routine services, while accident-only insurance is designed for eligible sudden injuries. Accident-only coverage does not protect against eligible disease treatment. A wellness add-on can repay some planned costs, depending on its terms.
When an accident-only plan may fit
Accident-only insurance may suit a tighter budget when an owner can handle illness costs without insurance. It generally pays only for eligible sudden injuries, not treatment for disease. A cat with an unexpected infection or chronic illness would need broader coverage for those costs.
Think about the bills you could pay without help. A lower premium may be useful when illness treatment remains within your emergency budget. It can be a poor trade if a disease diagnosis would force you to limit care.
What a wellness add-on can reimburse
Preventive-care options may reimburse vaccinations, annual wellness exams, flea and tick prevention, spaying or neutering and dental cleanings. These benefits address planned services, not unexpected illness. Some carriers’ preventive add-ons may take effect immediately.
Compare the annual reimbursement schedule with your expected routine expenses. A plan that repays set amounts may not match the full cost of every visit or service. The Best Friends overview of pet insurance distinguishes routine care from coverage for unexpected veterinary costs.
Add up the services you expect to use before paying extra for a wellness option.
Is Cat Insurance Worth the Cost?
Pet insurance is most valuable to owners who want help managing an unexpected bill they could not comfortably pay from savings. A U.S. policyholder survey found that 67% said pet insurance was worth the cost. Value and satisfaction differed among policyholders.
What policyholders say about value
In a survey conducted in December 2024 and January 2025, 53% were very or completely satisfied, 33% were somewhat satisfied and 14% expressed some degree of dissatisfaction.
Also, 34% said they saved more on pet care than they spent on premiums and deductibles. Another 20% said they broke even. Those results show that a policy can feel valuable even when a household’s claims do not exceed its costs.
Decide based on your emergency budget
Insurance trades a predictable premium for help with certain large, unexpected bills. Some years may bring few claims, while a sudden illness or injury can create a bill that exceeds savings. The policy only helps with eligible care, so it cannot remove every cost.
Consider these questions before enrolling:
- How much emergency savings is available?
- Could you manage the deductible when a claim arises?
- Can you keep paying the premium over time?
- How much do you value access to eligible care?
A policy is a better fit when its premium is sustainable even in a year with no reimbursement.
How Do You Compare Cat Insurance Quotes?
The fairest comparison uses matching cat details and identical policy settings, not the lowest number on a quote page. Premiums can change with age, breed, location, deductible, reimbursement rate and annual coverage limit. A lower monthly premium can mean a higher deductible or less coverage.
Compare matching policy settings
Use the same cat profile and policy choices for each quote. Then compare these items in order:
- Enter identical cat details, including age, breed and location.
- Compare accident-and-illness coverage with the same coverage type elsewhere.
- Match the annual coverage limit and deductible.
- Match the reimbursement rate and claim calculation.
- Compare waiting periods and exclusions.
- Check direct-vet payment options and fees.
The Costco pet insurance monthly premium is not a fixed national amount. A quote depends on the cat’s age, location and selected plan settings. Compare a current Costco quote with equivalent coverage elsewhere, not with a different plan’s headline price.
Check membership-linked offers carefully
Membership-linked pricing should be judged by eligibility, policy terms and the final premium. A discount may not help if it comes with a higher deductible, lower limit or exclusion that matters to your cat. Check any service fees as well as the monthly amount.
Compare matching policy terms before calling a lower quote a better deal.
Save the declarations and exclusions for each finalist so the policy terms can be checked before enrollment.
Conclusion
The right policy is the one whose covered care and out-of-pocket terms fit both your cat and your budget. ASPCA is our broad-coverage recommendation, Lemonade is a budget-focused alternative, and MetLife is worth comparing for multiple pets.
Request matching quotes for your cat, then compare the annual limit, deductible, reimbursement rate, waiting periods and exclusions. A quote only helps when those terms match the care and costs your household can manage.
Compare two or three matching quotes and read the exclusions before you enroll.